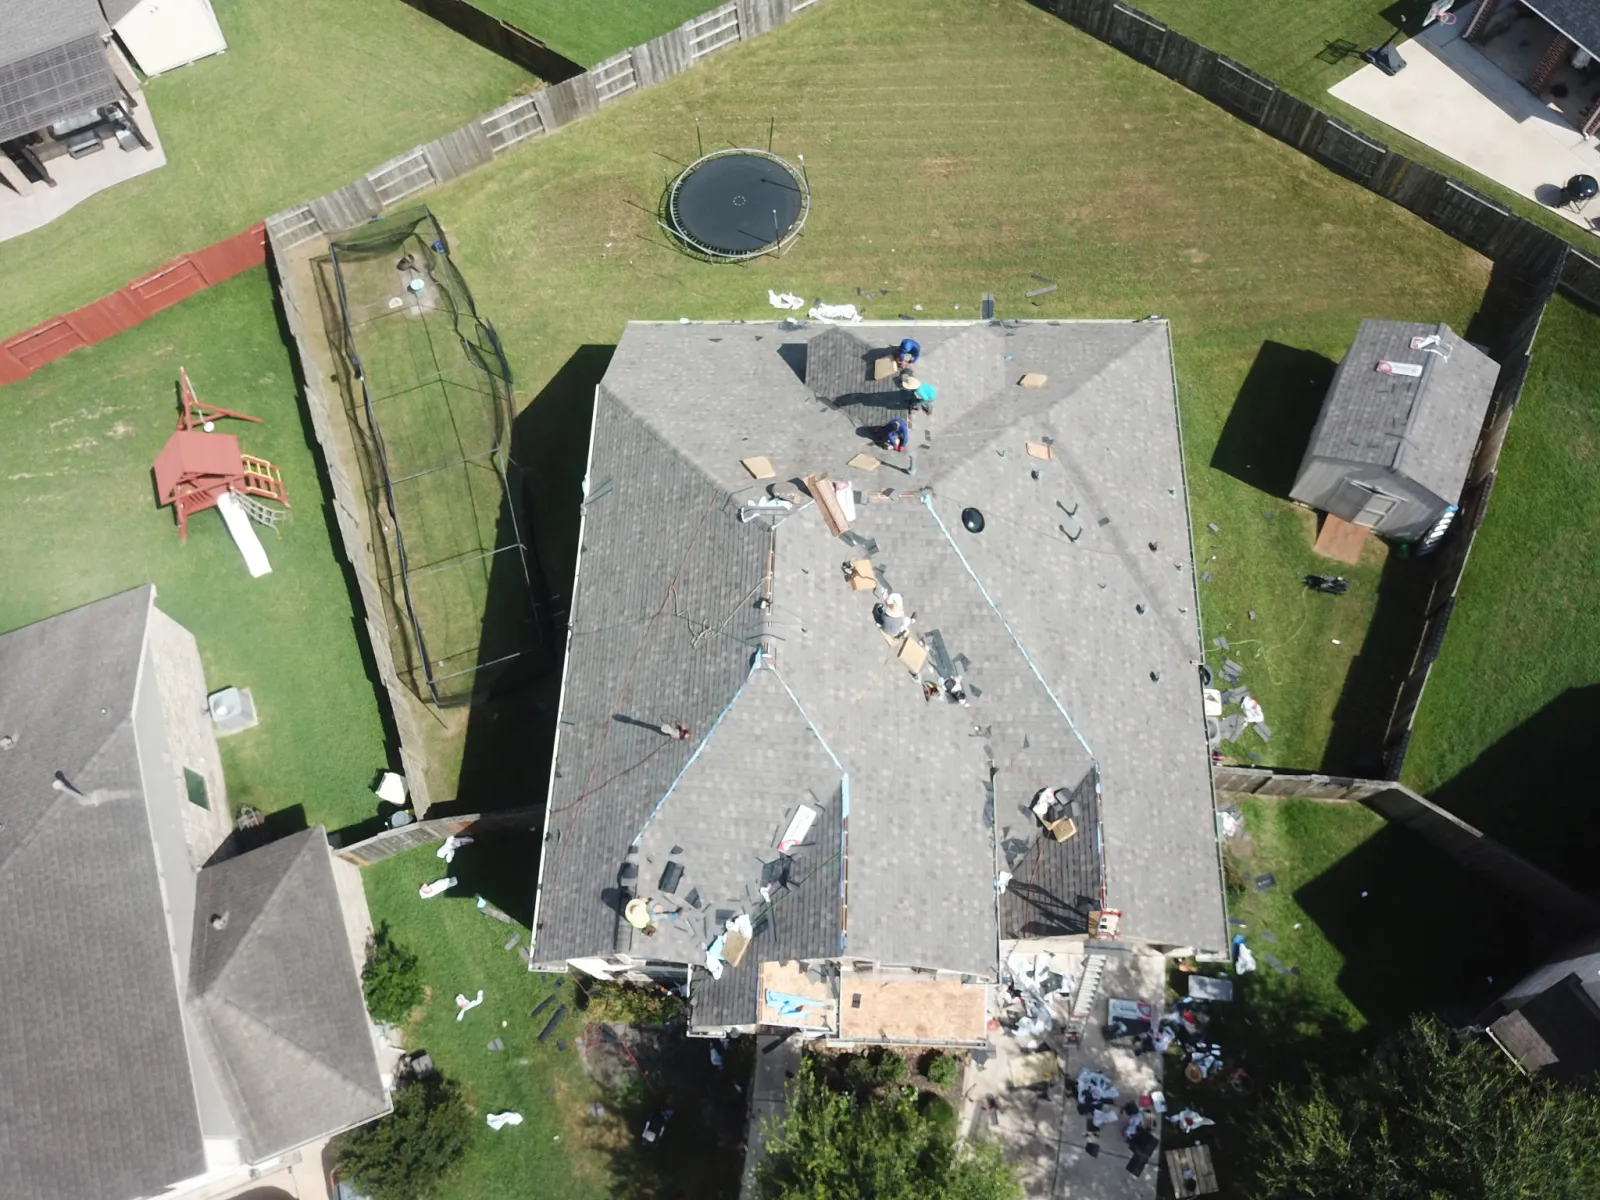
What carriers usually will and won't pay for
The single biggest reason claims get denied is that the damage was never properly documented — not that it wasn't there.
Usually covered
Sudden, identifiable storm events — hail bruising, wind-lifted or missing shingles, impact damage from a limb or debris.
Usually not covered
Age, granule loss from ordinary wear, long-standing leaks that were never dealt with, and poor previous workmanship.
The grey area
Older roofs with real storm damage on top of ordinary wear. This is where thorough documentation decides the outcome.
From claim to final nail
Insurance roof replacement is mostly paperwork and evidence. Here's the order it happens in, and who does what.
Free inspection
We get on the roof, find and photograph the damage, and tell you honestly whether you have a claim worth filing.
You file the claim
You open it with your carrier — it has to come from you. We give you the documentation to file it accurately.
We meet your adjuster
We're there when they inspect, walking them through what we found so nothing legitimate gets overlooked.
Approval and scope
The carrier issues a scope and payment. We check it against the actual roof and flag anything missing.
We build the roof
A complete system, upgraded ventilation and accessories included, finished in one to two days for most homes.
Final paperwork
We provide the invoice and completion documentation your carrier needs to release the remaining payment.
Why homeowners let us handle the claim
We do a lot of these. The Gulf Coast gives us plenty of practice.
We deal with the adjuster
You shouldn't have to argue about shingle grades with your insurer. That's our job, not yours.
Evidence, not opinions
Photographed, itemised damage that stands up to scrutiny — the difference between an approved claim and a denied one.
No deductible games
We won't waive or hide your deductible. It's fraud, and a roofer willing to defraud your insurer will happily cut corners on your roof.
What neighbours say about the work
Real 5-star Google reviews from homeowners and businesses across Baytown and Greater Houston.
“Wonderful family owned company. Having them work with my State Farm adjuster doubled State Farm's original settlement offer.”
“Wonderful team at Now Roofing. Got insurance to cover my whole roof! Would definitely recommend.”
“Outstanding experience with Now Roofing! From handling the insurance details to completing the job with precision.”
Related
- Insurance roof inspection — the documentation step, before you file
- Storm & hail damage — how we handle storm restoration
- Roof replacement — replacing a roof outside of a claim
- Roofing near me — check we cover your part of Houston
Storm damage you think should be covered?
Get a free inspection first. We'll tell you honestly whether you have a claim worth filing — and if you don't, we'll say so.
Common Questions
Insurance Roof Replacement Questions, Answered
What Houston-area homeowners ask about claims and replacements
Straight answers about getting a roof replaced through an insurance claim.
Will insurance pay for a full roof replacement?
What's the difference between ACV and replacement cost?
Do I still pay my deductible?
My claim was denied. Is that the end of it?
Will filing a claim raise my rates?
What OurCustomers Say
Real 5-star Google reviews from Baytown & Greater Houston homeowners
Get your free roof inspection
Storm damage, a leak, or an aging roof — we'll inspect it, show you the photos, and give you a straight answer.
- Fast Response
- Free Inspection
- Insured & Warrantied